
Summary
- Morgan Stanley has engineered one of the most impressive turnarounds of any bank in the post-GFC era.
- And in many respects it's a bank I like, with moat-like leadership positions in equity trading and underwriting and a first class wealth management business.
- However, while it currently looks very cheap on a forward P/E of just 8x there are growing downside risks to estimates that may make this "cheapness" an illusion.
- Ultimately MS remains a highly cyclical business and as we enter what at best looks like a choppier period for markets and at worst a turn in the market cycle, this isn't the time to be buying.
MS's valuation is enticing
MS is trading close to 2-year lows and it has delivered the weakest year-to-date returns of the large-cap US banks (+4% vs +10% on average for JPM, BAC, C and GS).
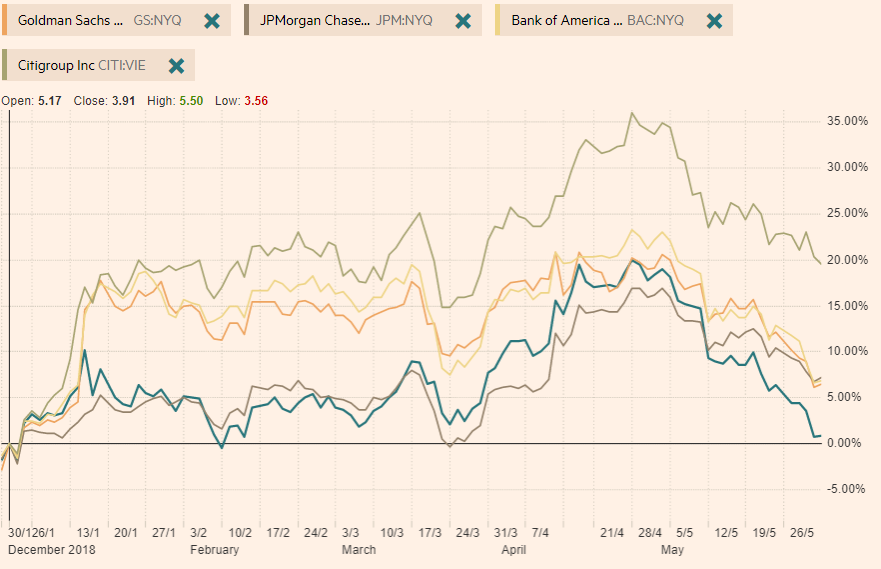
Source: FT markets data
This has pushed headline valuation multiples down to very low levels with a 1-year forward P/E being just 8.2x against a 5-year average of 12.7x and P/TNAV of close to 1x against a 5-year average of 1.2x.

