
Summary
- Despite disappointing earnings, Visa has been seeing a rebound in payment volumes of late.
- However, a second wave of COVID-19 and an intensifying competition from Mastercard remain two key risks.
- I take a long-term bullish view on the stock, but I am more neutral in the short term.
- Back in June, I made the argument that Visa (V) would see further upside going forward, as a result of continued growth in Total Payments Volume, as well as a growing trend towards digital payments more generally.
- That said, I did caution that the company could see some pressure in the near term, owing to a reported decline in credit card volumes.
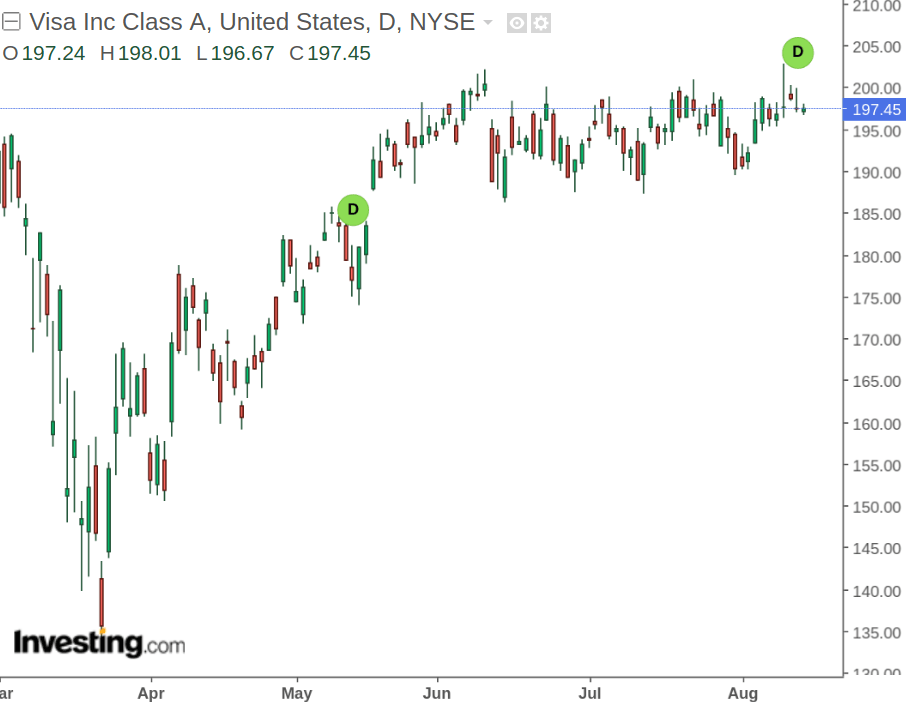 Source: investing.com
We can see that, after a strong rebound into June, the stock has largely trended stationary since then.
Moreover, Q3 2020 results were disappointing owing to the ongoing impact of COVID-19, with net income and earnings per share down by 24 and 23 percent, respectively.
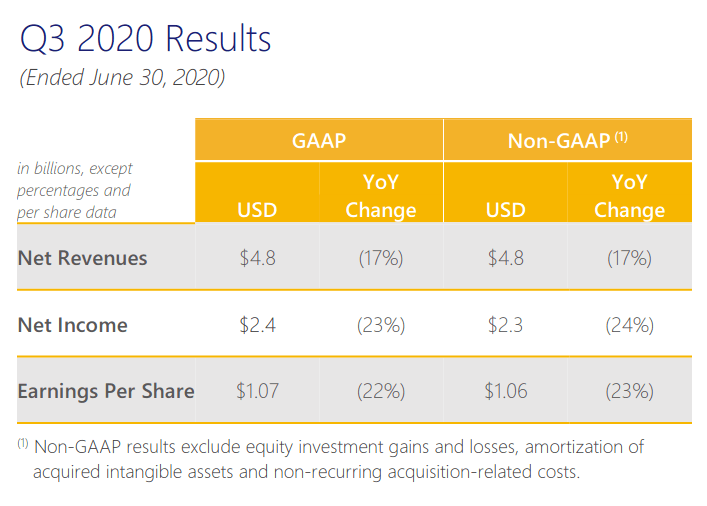
Source: Visa Fiscal Third Quarter 2020 Results
With this being said, Q3 results appear to be accounting for the sharp drop in payment volumes that happened just after lockdown took effect at the beginning of the quarter.
We can see that U.S. Payments Volume and Processed Transactions have rebounded into positive territory:

